Browse categories
Explore
Fiverr Pro
English
$
USD
Former Bank Manager, Excel Reconciliations, Loan Calculators and Data Cleaning
Need an IFRS 9 expected credit loss (ECL) calculation your auditors can follow? I'll build it in Excel with clear formulas, not a black box.
I'm a former bank manager with 8 years in accounting and audit, and an MBA in Finance.
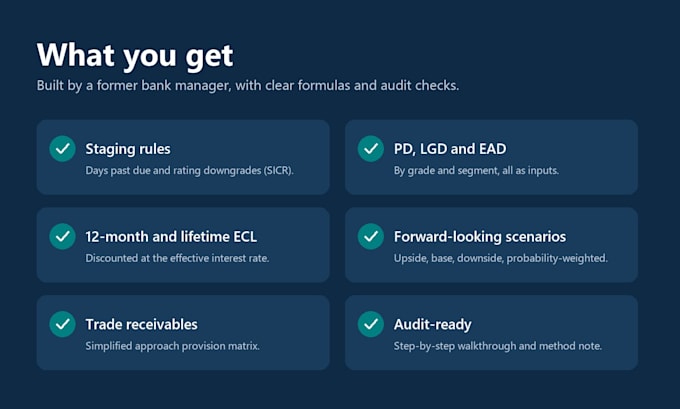
What you get:
Suits banks, non-bank and microfinance lenders, fintech and leasing companies, and any IFRS reporter with trade receivables.
You send your loan list or receivables ageing; I build, test and explain the model. Your data stays confidential.
Please note: I build the model and document the method. Final accounting judgements rest with you and your auditors.

Please note that there is no screening process for this service. We recommend that you message the freelancer and check all necessary details before placing your order. Read more about Financial services at Fiverr.
What data do you need?
A loan list (balance, interest rate, maturity, rating or days past due, segment) or a receivables ageing report. Excel or CSV is fine, and anonymised IDs are fine.
Can you build PD and LGD from my own history?
Yes, in the Premium package, if you have default and recovery history. Otherwise I use your assumptions or clearly labelled proxies.
Will my auditors accept it?
It is built to be audited: every number traces back to inputs, with a walkthrough and method note. Acceptance depends on your assumptions and your auditor; I'll help answer their questions about the model.
Does it work for Ind AS 109 or other IFRS-based standards?
Yes. The same approach applies; tell me your standard and I'll adapt the labels and disclosures.
Is my data safe?
I use your data only to build your model, and anonymised loan IDs are fine.