Browse categories
English
$
USD
Connect to your AI
Crypto Trading Tool Developer, Python and Pine Script
Your strategy looks profitable on TradingView but loses money live? I'll find out why.
I audit your backtest logic and rebuild it realistically in Python to uncover what the Strategy Tester is hiding.
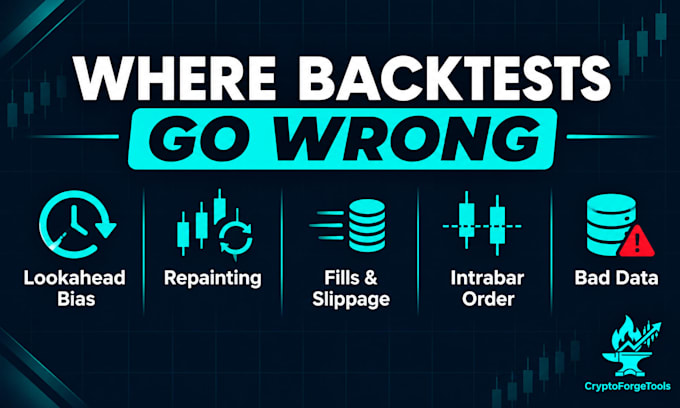
What I check:
Lookahead bias and repainting
Fill, slippage and commission assumptions
Intrabar order of stops vs targets
Data issues (contract rolls, gaps, bad bars)
Pine Script logic vs what actually executes
What you get:
Causes ranked by impact
Plain-English written findings
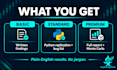
Higher tiers: Python replication, walk-forward and Monte Carlo results, full PDF report
I recently traced a futures strategys gap to data splice errors and exit-order bugs, then validated the rebuild against TradingViews own exports.
Ill be honest: if the edge isnt there, I'll say so. This is analysis and debugging only, with no trade advice and no profit guarantees.
To start, message me your strategy code or rules, market, timeframe, and the backtest vs live results youre seeing.
Platform:
TradingView
•
Binance
Development technology:
Python
•
PineScript
Do I need to share my Pine Script code?
Code is best. If you can’t share it, send detailed rules (entries, exits, stops, sizing) and I’ll work from those, though findings may be less precise.
Which platforms and markets do you support?
TradingView/Pine Script strategies mainly, on crypto, futures and forex. Other platforms are possible, so message me first.
Will you tell me if my strategy is profitable?
I’ll tell you what the data shows, including if there’s no edge. I can’t promise profit or give trade advice.
What do I need to provide?
Your strategy code or rules, market, timeframe, date range, and your live trade history or screenshots, plus the TradingView backtest results.
Will you fix my strategy too?
his gig finds and explains the mismatch. Rebuilding or overhauling the strategy is separate work, so message me for a custom quote.
How is this different from a normal backtest?
A normal backtest runs your strategy. This one explains why your existing results disagree with reality.