Browse categories
Explore
Fiverr Pro
English
$
USD
Python Developer for Crypto Trading Bots and Backtests
Before you risk real money on a trading strategy, find out if it actually has an edge. I turn your rules into Python and backtest them on 12 months of real crypto exchange data (Bybit, Binance and similar) - with taker fees and slippage on every trade.
Most backtests look great because they ignore costs, peek into the future or fit the past too closely. Mine use conservative fills (stop counted first), proper indicator warm-up and no lookahead.
You get:
Standard adds out-of-sample and parameter sensitivity tests; Premium adds walk-forward, Monte Carlo and a 2x cost stress test.
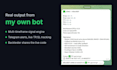
I hold my own work to the same standard: my signal strategy (627 trades, real fees) scored profit factor 0.58 - no edge - and I published that result.
Good fit: indicator-based crypto strategies, swing or intraday. Not a fit: guaranteed-profit promises or tick-level HFT.
Message me your rules before ordering - I'll confirm what's testable.
Platform:
TradingView
•
Custom
•
Binance
Development technology:
Python
Can you guarantee my strategy will be profitable?
No, and nobody honest can. I test your exact rules on real data with real costs and tell you what the numbers show. If there is no edge, you find out before risking money.
What do you need from me to start?
Your strategy rules (entries, exits, position sizing), the exchange and pairs, and the timeframe. A screenshot of a chart with marked trades helps a lot. I confirm the rules with you in writing before coding.


