Browse categories
Explore
Fiverr Pro
English
$
USD
Most backtests answer the wrong question.
"My screen made +4% over 20 days" tells you what those 20 days
did. It does not tell you whether the screen selected anything.
I run one comparison: your picks against same-day random draws
of the same size, from the same pool you could have picked from.
WHAT I NEED FROM YOU:
picks CSV: date, name
universe CSV: date, name, fwd_ret
I am not a licensed financial adviser and hold no financial
licence or certification. This is a statistical comparison of
numbers you supply. It states what that comparison supports. It
does not tell anyone what to do with their money, and it does
not predict any future result. No specific return, earnings
figure, or profit rate is stated or implied anywhere in the
deliverable.
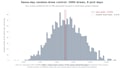
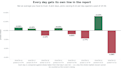
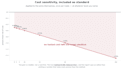
SEE IT BEFORE YOU BUY. The sample report in my portfolio is exactly
this package run on a real pair of files: 99 picks over 8 days, 197
names priced, picks varying 6-22 per day against a pool of 25-59.
Observed -0.4961% against a control mean of -0.4096%, percentile
0.4775, 2,000 draws. The verdict printed was NOT ESTABLISHED. I ship
the failures too.

Programming language:
Python
Technology:
Other
Analysis Type:
Quantitative Analysis
•
Statistical Analysis
Tools:
Other
Can you pick stocks for me?
No. I measure a screen you already have.
Do I need a data subscription?
No. You supply the two CSVs, or raw price data.
What if the answer is no?
That is a real deliverable, and it is the one in my portfolio samples. See it before ordering.
Can you promise my screen works?
No. What I deliver is the comparison, not a promise about what happens next.
Can you work from my Python or Pine Script strategy?
Send the output as picks + universe CSVs and yes. Porting the strategy itself is a separate order -- message me first.


