Browse categories
English
$
USD
Connect to your AI
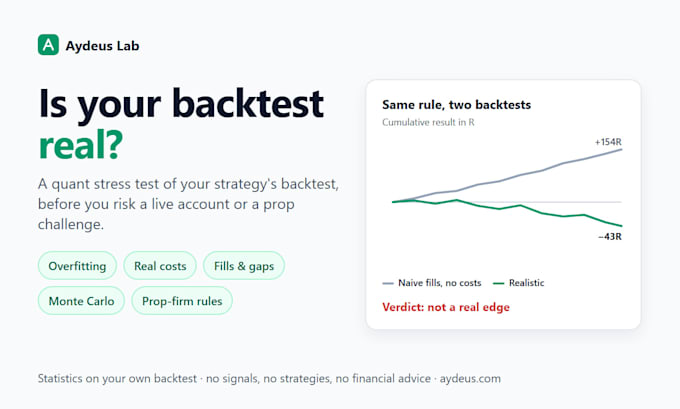
Most backtests that look great fail live. Not because of bad luck: because of look-ahead, wrong time zones, fills nobody could get, costs, or simply testing too many variants.
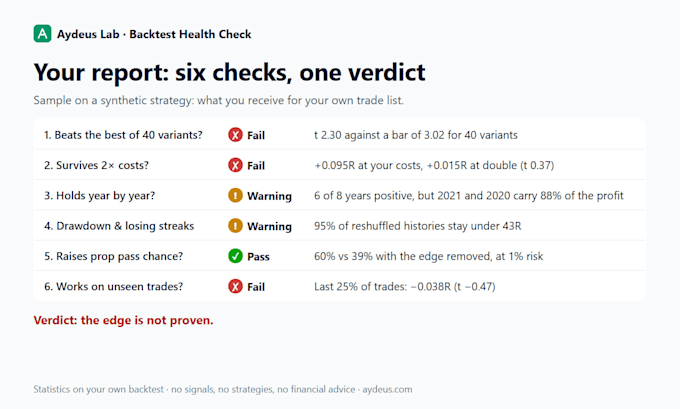
I check your backtest the way a quant fund would, using the published 12-gate standard of Aydeus Lab (aydeus.com/methodology), where every test is public with its code and outputs.
You get a clear report: what holds up, what breaks, and why.
I analyze the statistics of the backtest you provide. I do not sell trading strategies or signals and I do not give financial advice.

Will you make my strategy profitable?
No. I tell you whether the profit in your backtest is real. Optimizing parameters until a backtest looks good is exactly what this check catches.
Do you need my code?
Basic needs only the trade list. Standard and Premium need the rules in writing (or Pine Script, MQL5, Python).
Which data do you use?
Yours: the history from your own broker, so the test uses your real spreads. For Nasdaq-100 strategies I can also use licensed futures data.
Can you tell me whether to trade it?
No. The report states statistics; the decision is yours.
What if it fails?
Then you saved the cost of a challenge or a live account. The report shows exactly which check failed.