Browse categories
English
$
USD
Connect to your AI
Backtest Doctor, MD, MBA, Strategy validation
Is your crypto trading edge real, or just a backtest illusion?
Most backtests look great and fail live. Common causes:
I am a medical doctor (MD) with an MBA in Finance, and I review strategies the way a doctor reads a scan: evidence first, clear conclusion.
HOW IT WORKS
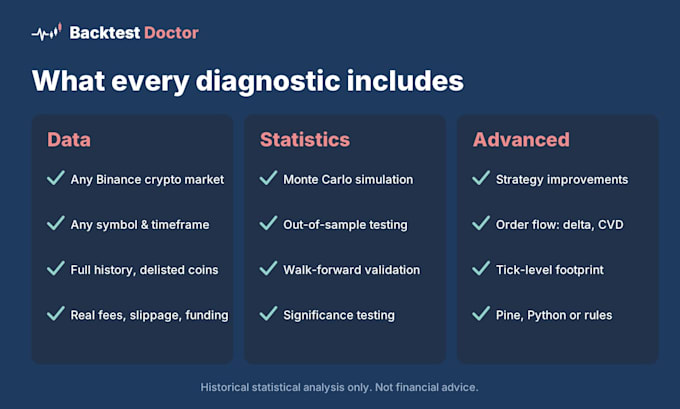
Your strategy (Pine Script, Python or written rules) is implemented on my custom Python backtesting engine and tested on any Binance crypto market, symbol and timeframe, across the full history, with real fees, slippage and funding. Delisted coins are included, so there is no survivorship bias.
STATISTICAL TESTING
Monte Carlo, out-of-sample and walk-forward validation, parameter robustness and significance testing.
MORE THAN A VERDICT
I test improvements to your strategy, validated on unseen data, plus order flow (delta, CVD) and tick-level footprint analysis.
YOU RECEIVE
A structured diagnostic report with an Edge Score from 1 to 5, a clear explanation of where and why the strategy fails, and concrete suggestions for improvement.
Your strategy stays confidential.
_yh4n1d.jpg)
Platform:
TradingView
•
Custom
•
Binance
What do I need to send you?
Your Pine Script, Python code or a clear description of the rules (entry, exit, stop loss, take profit), the coins and timeframe, and if possible your TradingView trade list or trade list from any platform, so I can reconcile results trade by trade.
Which markets do you cover?
Crypto only, on Binance data: spot, USD-M and COIN-M futures, any symbol, any timeframe from 1 minute to daily, across the full available history. Stocks, forex and commodities are not covered.
Which biases do you check for?
Lookahead and repainting, overfitting, data snooping, selection bias, survivorship bias (delisted coins included), ignored fees, slippage and funding, unrealistic fills and insufficient sample size.
How do you improve a strategy without overfitting it?
Each variant is developed on one part of the data and validated on a separate, untouched part. The report states how many variants were tested and adjusts statistical significance accordingly.
What if my strategy has no edge?
You get an honest Edge Score with a clear explanation of where and why it fails, plus concrete suggestions for improvement. Knowing this before trading live is the point of the diagnostic.
Is my strategy kept confidential?
Yes. Your code, rules and results are used only for your diagnostic and are never shared or reused.
What data do you use exactly?
Official Binance historical data: spot since 2017, USD-M and COIN-M futures since 2019-2020, all symbols including delisted coins. Candles from 1 minute to daily, plus actual funding rates and tick-by-tick trades.
Do you have order flow and derivatives data?
Yes: tick-level trades (delta, CVD, footprint, imbalances), open interest and long/short ratios, mark and index prices, and aggregated order book depth snapshots. Full historical level-2 order book data is not available.
What is your refund policy?
Full refund if I cannot implement your strategy or miss the delivery date. If my code does not match your rules, I fix it free of charge. Results reflect what the data shows, so an unfavourable result is not grounds for a refund.