Browse categories
English
$
USD
Connect to your AI
Before you risk money on a strategy, find out if it actually works. I will backtest your trading strategy in Python with realistic costs, so you see honest numbers instead of a curve-fit fantasy.
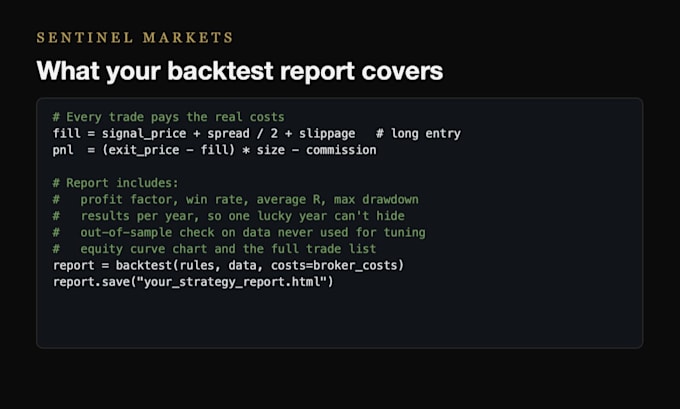
I have run hundreds of backtests on my own strategies (indices, forex, gold) and learned the hard way what makes results misleading: missing spread and slippage, look-ahead bias, and testing on the same data you tuned on. Your report avoids all three.
What you get:
You get a clear report in plain English plus the Python code, so you can rerun it yourself.
Please message me with your rules and the market before ordering. If your strategy needs special data, we will agree on the source first.
Note: A backtest is not a guarantee. I report what the data says, good or bad.
Platform:
Prop firm
•
MT5
•
Custom
Development technology:
Python
•
PineScript
•
MQL5
Where does the price data come from?
Free, reliable sources for most forex, indices, gold and crypto (for example Dukascopy). You can also send your own data or broker export. For markets that need paid data, we agree on it before you order.
What if the results are bad?
Then you just saved real money. I report honest results either way, and I will point out where the strategy loses (costs, certain years, certain sessions) so you know what to change or drop.